Applying for a car or apartment can be a big step. It can also feel stressful if you are not sure what your credit looks like. You may wonder whether your score is high enough, whether old accounts will hurt you, or whether something on your report could cause a problem.
The best thing you can do is check your credit before you apply. This gives you time to review your report, fix any mistakes, and make a plan. You do not need perfect credit to take the next step, but it does help to be prepared.
Whether you are trying to get approved for a car loan or a new place to live, a little planning can make the process feel easier.
Look at Your Credit Report First
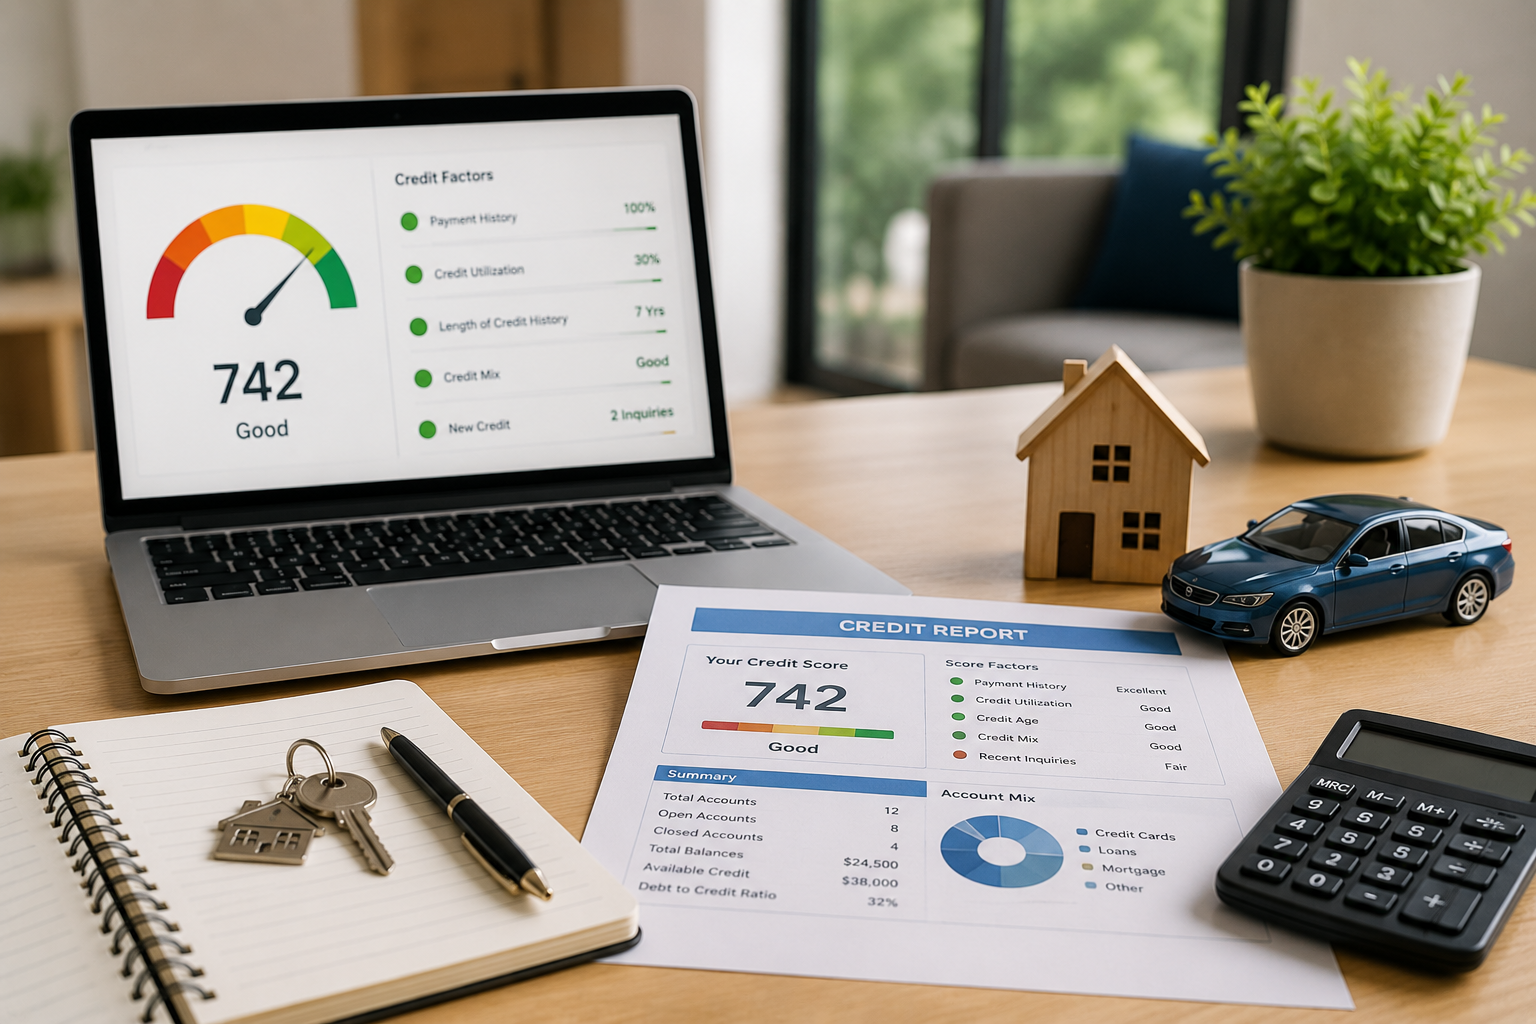
Before you fill out an application, take time to look at your credit report. Your report shows important details about your credit history. This may include your open accounts, closed accounts, payment history, balances, collections, and credit inquiries.
It is a good idea to check all three major credit reports. These come from Equifax, Experian, and TransUnion. The information may not be the same across all reports, so checking all three can help you see the full picture.
As you review your report, look for anything that seems wrong. You may find an account you do not recognize, a balance that looks off, a late payment you believe is incorrect, or an old item that should have been updated. Even small errors can make your credit look worse than it really is.
If you see something that does not look right, do not ignore it. It may be worth looking into before you apply. Taking care of potential errors in advance may help you avoid delays or surprises later.
Clear Tides Capital can help you review your credit report so you can better understand what may need attention before applying.
Know What Lenders and Landlords May Review
When you apply for a car loan, the lender will usually look at your credit score, income, payment history, current debt, and overall ability to repay the loan. Your credit can also affect the interest rate you are offered. In many cases, a lower score may lead to a higher rate or a larger down payment.
When you apply for an apartment, the landlord or property manager may also review your credit. They may want to see if you have unpaid balances, past collections, or a history of missed payments. Some landlords are stricter than others, so every situation is different.
Credit is only one part of the decision. Income, rental history, job history, references, and savings can also matter. That is why it helps to have your paperwork ready. For an apartment, this may include pay stubs, bank statements, identification, and rental references. For a car loan, you may need proof of income, proof of address, insurance information, and a realistic budget.
Being prepared shows that you are serious. It can also help you feel more confident when it is time to apply.
Take Small Steps Before You Apply
Once you know what is on your credit report, focus on simple steps that may help your credit look stronger.
Start by paying your bills on time. Payment history makes up 35% of your credit score — the biggest single factor. If you’re current, keep it that way. If you’ve missed payments in the past, focus on getting back on track and staying consistent going forward.
Next, take a look at your credit card balances. Carrying balances close to your limits can hurt your score, even if you’re paying on time. Paying balances down — even gradually — can make a real difference. Credit utilization accounts for 30% of your score, making it one of the easiest areas to improve quickly.
Be mindful about opening new accounts, especially right before a big purchase. Applying for several accounts in a short window can make your credit profile look riskier to lenders. New credit makes up 10% of your score, largely through hard inquiries. If you’re planning to shop for something like a car loan, compare your options first and go in with a plan — that way you’re not adding unnecessary inquiries while lenders are already reviewing your file.
It also helps to avoid big purchases before you apply. Taking on new debt right before applying for a car loan or an apartment can change how a lender or landlord sees your finances — even if the rest of your credit looks solid. Timing matters just as much as the numbers themselves.
Getting your credit ready doesn’t have to be complicated. Start by checking your report for errors, then focus on building the habits that keep your credit strong going forward. If you’re planning to apply for a car loan or apartment soon, don’t leave it to chance.
Clear Tides Capital can help you review your credit, catch what’s holding you back, and walk in prepared — not hopeful. Contact us today or schedule a free consultation to get started.